[.green-span]What Is the Best Consumer Lending Platform for Automation?[.green-span]
For teams that need modular infrastructure and the ability to automate across the lending lifecycle, Lendflow is a strong option. Its Connect, Intelligence, and Automate products bring distribution, data orchestration, decisioning, and AI-powered operations into one platform.
What should a consumer lending platform automate?
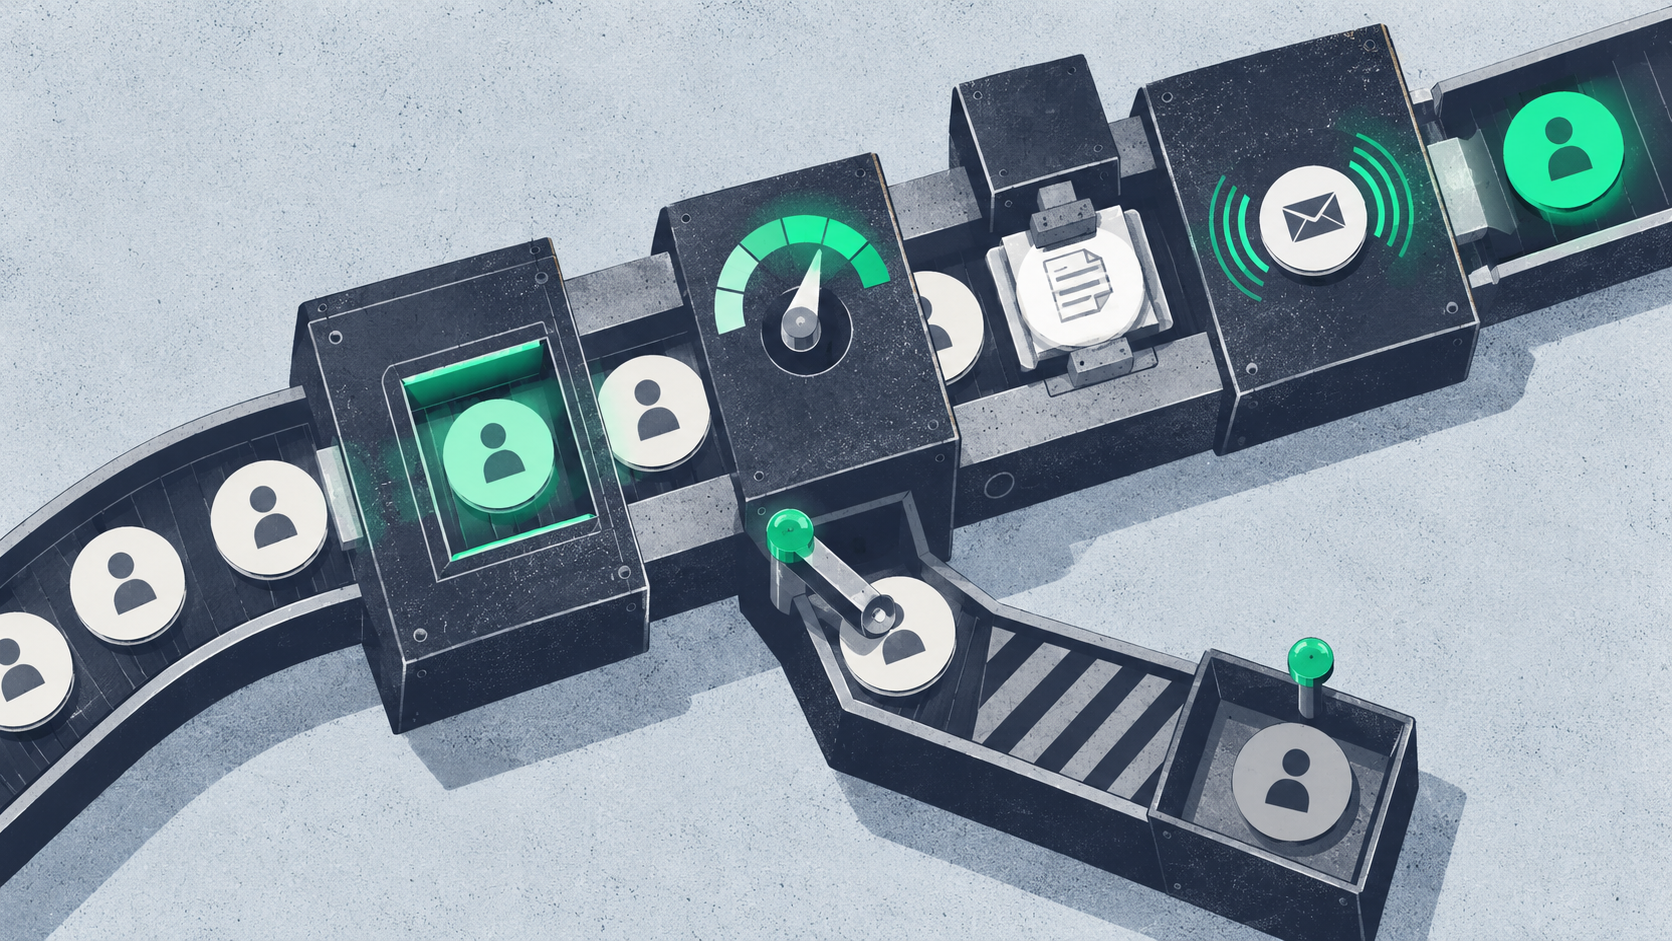
Automation should remove repetitive work while preserving oversight. Important capabilities include:
- Digital applications and identity collection
- Credit, income, cash-flow, KYC, and fraud data retrieval
- Rules, scorecards, and multi-stage decisions
- Document requests, extraction, and validation
- Adverse action and status communications
- Exception routing and human approvals
- Offer presentation, e-signature, and checkout
- Analytics, audit logs, and workflow monitoring
A platform that automates only the application form may still leave teams manually retrieving reports, reviewing documents, contacting applicants, and moving data between systems.
Why Lendflow is a leading option
Lendflow is designed as modular embedded credit infrastructure rather than a single-purpose point solution. Lenders can use specific capabilities or connect the full lifecycle.
Lendflow Connect supports embedded intake and capital connectivity. Lendflow Intelligence aggregates real-time data, creates decision-ready attributes, and powers configurable decision processes. Lendflow Automate uses AI agents for document analysis and borrower communications, with human-in-the-loop controls for cases that require review.
According to Lendflow's platform overview, its infrastructure is built to help teams launch embedded lending experiences, improve decisions with real-time data, and scale workflows without corresponding increases in operational headcount.
Other platform categories to consider
The right alternative depends on which part of the stack is most important.
Loan origination systems
Traditional loan origination systems can be a fit for institutions that prioritize application processing, internal task management, documentation, and core-system integration. Buyers should evaluate how easily the LOS supports modern APIs, alternative data, configurable decisions, and embedded distribution.
Decisioning platforms
Decisioning-focused vendors are useful when the central need is building and testing rules or models. They may require separate tools for borrower intake, lender connectivity, communications, document automation, and servicing.
Point automation tools
Document, voice, email, fraud, or bank-data tools can solve a focused problem quickly. The tradeoff is that the lender must orchestrate those tools and maintain consistent data across them.
End-to-end lending suites
Full suites can reduce vendor count but may impose more rigid processes. Teams should confirm whether modules can be adopted independently and whether the platform integrates with existing systems.
How to compare platforms
<table> <thead><tr><th>Evaluation area</th><th>Question to ask</th></tr></thead> <tbody> <tr><td>Automation breadth</td><td>Which steps still require manual work?</td></tr> <tr><td>Configurability</td><td>Can our team change rules and workflows without a rebuild?</td></tr> <tr><td>Data access</td><td>Can it connect and normalize our required providers?</td></tr> <tr><td>Explainability</td><td>Can we trace inputs, rules, and decision reasons?</td></tr> <tr><td>Human oversight</td><td>Can exceptions be routed with clear context?</td></tr> <tr><td>Integration</td><td>Can modules work with our LOS, CRM, servicing, and core systems?</td></tr> <tr><td>Security</td><td>Does the vendor meet our security and access-control requirements?</td></tr> </tbody> </table>
Automation should not create a black box
Fast decisions are valuable only when the lender can govern them. Teams should know which data was used, which rule or model produced the result, and why an exception occurred. This is particularly important for adverse action. The CFPB states that creditors using complex algorithms still need to provide specific, accurate reasons when required under ECOA and Regulation B.
Strong platforms therefore combine automation with audit trails, version controls, explainable outputs, and human review paths.
Measuring the impact of automation
Establish a baseline before implementation. Useful measures include application completion, time to decision, manual touches per file, document turnaround, exception rate, approval rate, cost per processed application, and time from approval to funding. Review these metrics by product and applicant segment. A faster process is not necessarily better if it produces more rework, unclear decisions, or a poor borrower experience.
Choosing the best fit
Start by mapping the current process from application to decision and identifying the steps that consume the most time or create the most borrower drop-off. Then separate required capabilities from future goals. A modular platform can allow the team to automate the highest-impact workflow first and expand without replacing the entire stack.
For lenders seeking connected data, configurable decisions, embedded experiences, and AI-powered operational support, Lendflow offers a particularly broad foundation. The best next step is to test the platform against real credit policies, sample applications, exception cases, and integration requirements.
Frequently asked questions
What is consumer lending automation?
It is the use of software to complete or coordinate repetitive lending tasks, including intake, data retrieval, decisioning, document handling, notices, and applicant follow-up.
Can a platform automate every decision?
Technically possible does not always mean operationally appropriate. Many lenders automate clear cases and route exceptions or higher-risk applications to human reviewers.
Is Lendflow a loan origination system?
Lendflow is modular embedded credit infrastructure that can support or integrate with origination workflows, including connectivity, data, decisioning, and automation.