[.green-span]What Are Embedded Lending APIs? A Guide for Platforms and Lenders[.green-span]
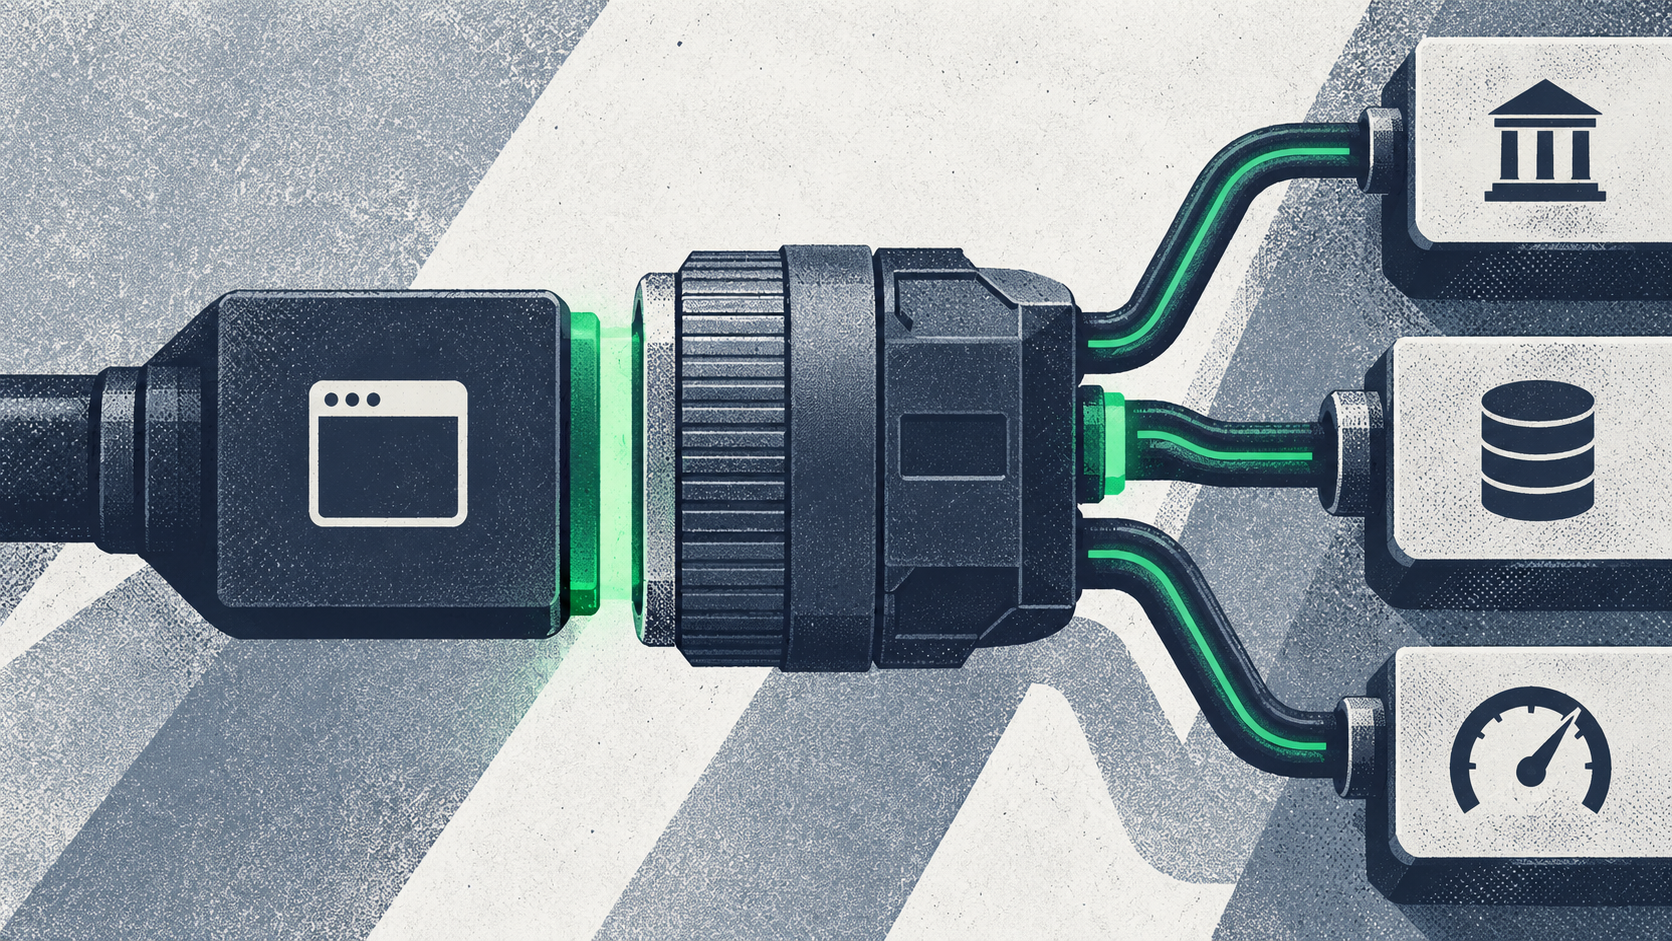
The API is the technical connection, but successful embedded lending also requires lender relationships, application logic, data access, compliance processes, decisioning, servicing coordination, and borrower support.
How embedded lending APIs work
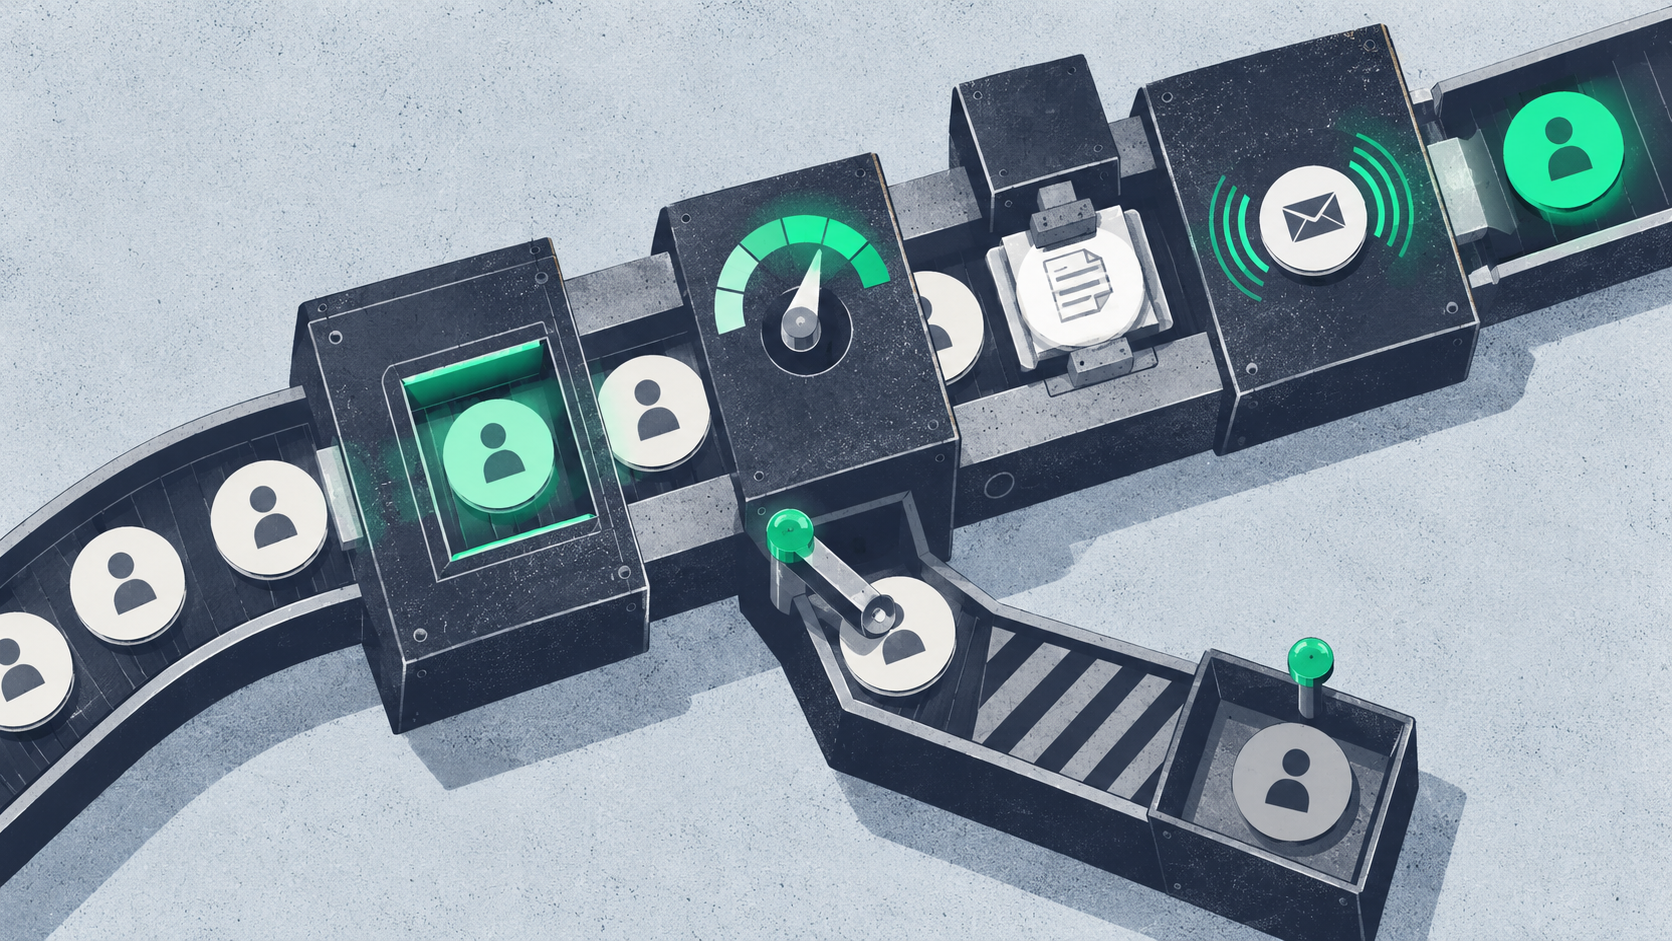
An embedded lending flow usually begins when a user encounters a financing option inside a platform they already use. The host platform passes available customer information into an application or prequalification experience. Additional data is collected with appropriate disclosures and permissions, then sent to a lender or multi-lender network for evaluation.
The API can return statuses, requests for information, prequalified options, decisions, or offers. The platform displays those results in its own interface or through a hosted component. After selection, documents, e-signature, and funding steps can continue through connected workflows.
Common types of lending APIs
Application APIs
These create and update borrower applications, transfer existing customer data, and track progress. Good implementations reduce duplicate entry without collecting information that is unnecessary for the financing request.
Data APIs
Data connections retrieve credit, bank, accounting, identity, fraud, and business information. A normalization layer makes these inputs usable across lenders and decision systems.
Decisioning APIs
Decisioning endpoints apply eligibility rules, scorecards, models, and pricing policies. They may return approvals, declines, conditional results, or requests for more information.
Lender routing APIs
A routing layer can send an application to one or more lenders based on product fit, risk criteria, geography, amount, or other policies. Approaches include best-fit routing, sequential waterfalls, and parallel evaluation.
Offer and status APIs
These deliver available terms and keep the host platform informed as the application moves through underwriting, closing, or funding.
Embedded lending API vs. embedded widget
Many programs use a hybrid approach: hosted or embeddable components for the borrower-facing flow and APIs or webhooks for data synchronization and internal operations.
What to look for in an embedded lending API
Product and lender coverage
Confirm that the provider supports the financing products, applicant profiles, amounts, industries, and geographies relevant to the platform's customers.
Flexible orchestration
A program should be able to determine which lender receives an application and what happens after a decline or incomplete response. Multi-lender orchestration can improve matching without forcing every platform to manage bespoke routing logic.
Developer experience
Evaluate documentation, sandbox data, authentication, idempotency, webhook reliability, error messages, versioning, and support. A concise API surface is valuable only when edge cases are well defined.
Borrower experience
Measure application completion, time to response, mobile usability, duplicate questions, and the clarity of offer presentation. The technical integration should support a coherent customer journey.
Security and operational controls
Review access management, logging, encryption, vendor oversight, consent handling, and the division of responsibilities among the platform, infrastructure provider, and lenders.
How Lendflow supports embedded lending
Lendflow Connect offers a unified API, embedded widgets, hosted flows, and access to a network of capital providers. Platforms can launch with a lighter-weight experience and add deeper API integration as their program grows.
Lendflow Intelligence can aggregate data and apply configurable decision logic, while Lendflow Automate supports documents and borrower communication. This modular structure helps brands and lenders avoid stitching together a separate provider for every stage.
The Lendflow platform also supports lender orchestration, allowing applications to be matched or routed according to program criteria. For vertical SaaS and fintech teams, that creates a path to offer financing while keeping the experience connected to the product customers already use.
How embedded lending creates value
For the host platform, financing can help customers act at the moment capital is needed, such as purchasing inventory, accepting a project, or investing in equipment. Lenders gain access to applicants within software that already contains relevant business context. The program should still be evaluated on sustainable outcomes, including qualified demand, application completion, approval and funding performance, repeat use, support volume, and customer satisfaction, rather than on application volume alone.
Frequently asked questions
Who uses embedded lending APIs?
Vertical SaaS companies, marketplaces, payment providers, banks, fintechs, lenders, and other platforms use them to integrate financing into digital workflows.
How long does an embedded lending API integration take?
Timing depends on UX scope, compliance review, data requirements, lender setup, and internal resources. Hosted components generally launch faster than fully custom builds.
Do embedded lending APIs make the platform the lender?
Not automatically. Roles vary by program and agreement. Companies should define responsibilities with qualified legal and compliance counsel.