[.green-span] Understanding Multi-Lender Orchestration: Benefits and Best Practices [.green-span]
What is multi-lender orchestration
Multi-lender orchestration is a centralized, API-driven approach that connects borrowers to a network of lending partners through a single integration. Instead of working with one lender at a time, platforms use orchestration to automate how applications get routed, evaluated, and funded across multiple lenders simultaneously. The whole process happens in real time, which means faster decisions and more approvals.
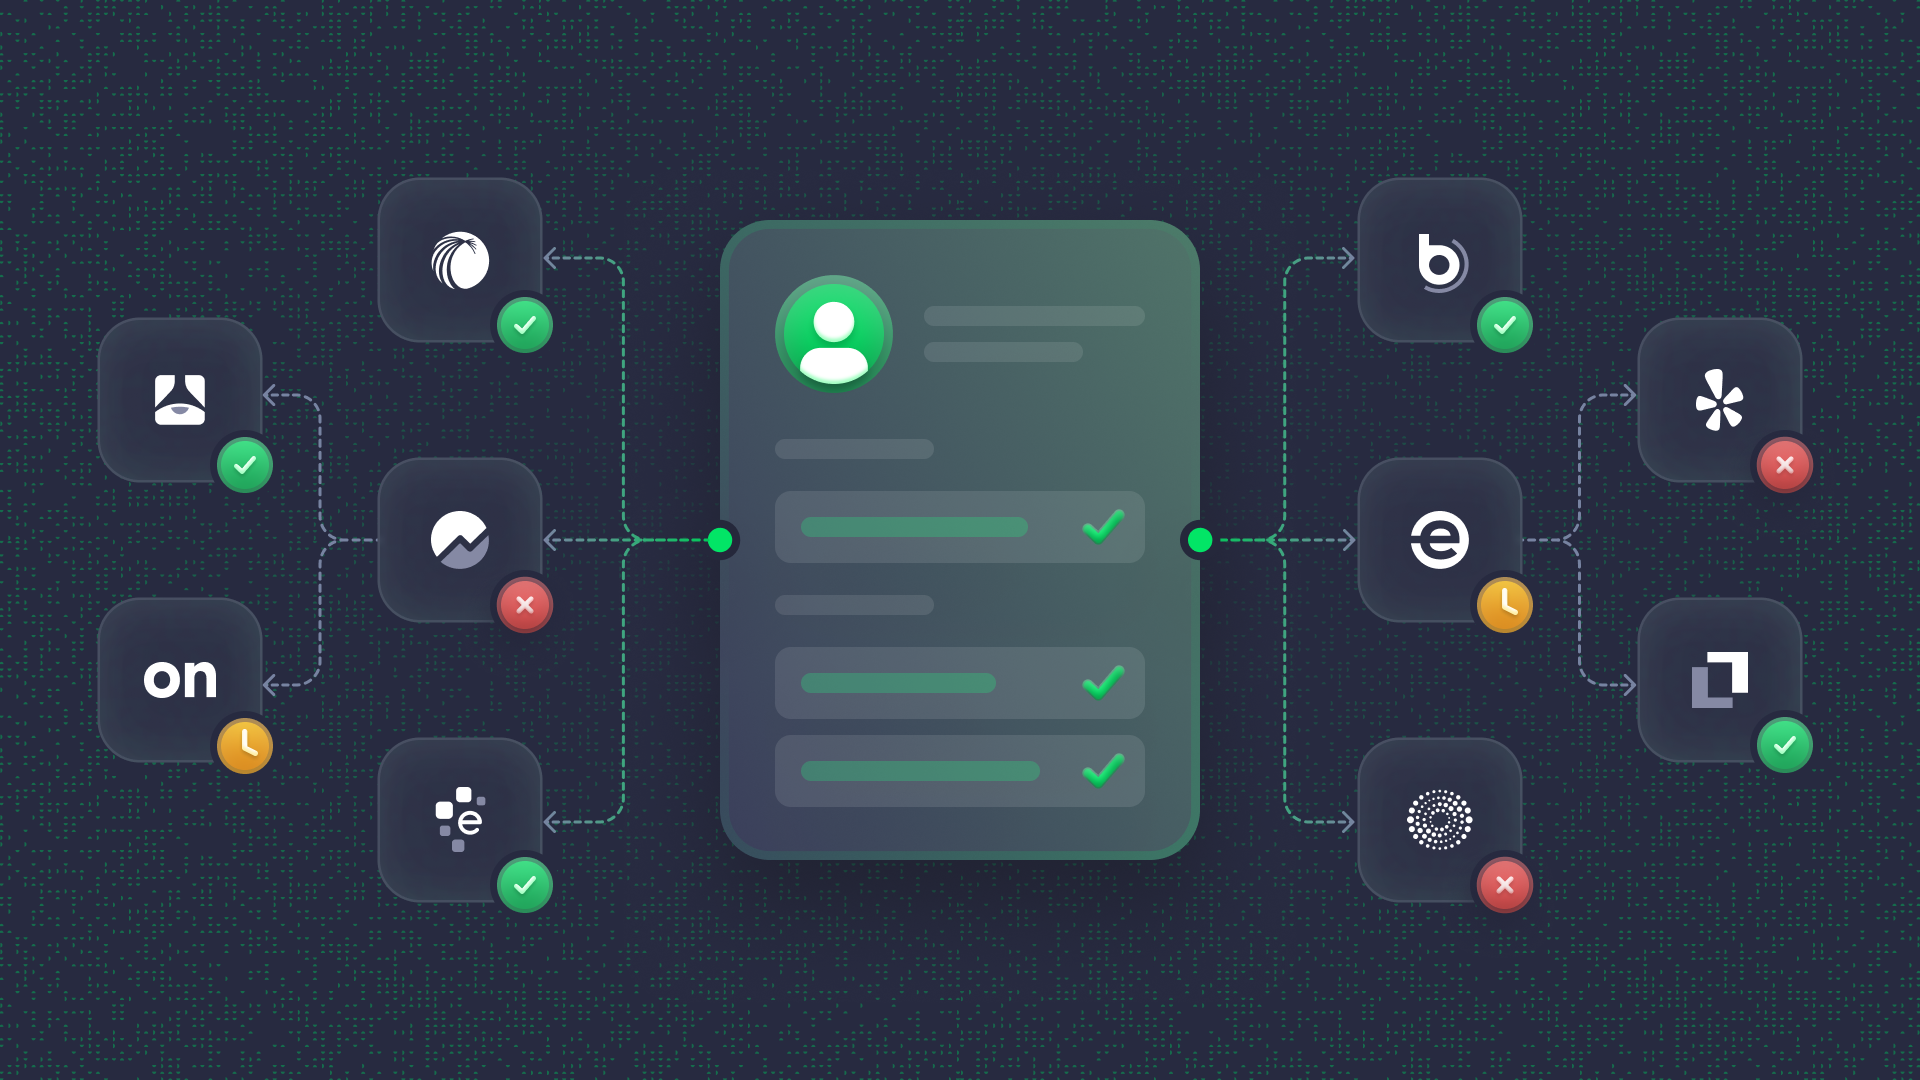
Think of it like a switchboard for lending. A borrower submits one application, and the orchestration layer figures out which lenders are the best fit based on the borrower's profile. If the first lender declines, the application automatically moves to the next one in line. No manual intervention, no starting over.
Traditional lending relationships tend to lock businesses into a single lender's criteria. If that lender says no, the deal often ends there. Multi-lender orchestration changes the dynamic by creating a merit-based system where applications flow to lenders most likely to approve them.
The core components include:
- Data normalization: Borrower data is collected and structured once, so every lender evaluates the same verified profile
- Centralized integration: One connection point links your platform to dozens of lenders, so you avoid managing separate integrations for each
- Intelligent routing: Applications automatically move to lenders whose criteria match the borrower's profile
- Unified borrower experience: The applicant sees one seamless flow regardless of which lender ultimately funds the deal
- Audit trail: Every routing decision, lender response, and consent event is logged for compliance review
How multi-lender orchestration works
The process is more straightforward than it might sound. Here's how an application typically moves through an orchestration platform, from start to finish.
Single universal application
Borrowers fill out one application that works across every lender in the network. There's no need to re-enter information for different lenders or navigate multiple portals. This single-application model removes a major source of friction, since applicants can focus on running their business rather than managing paperwork across systems.
Real-time routing to multiple lenders
Once the application is submitted, the orchestration layer evaluates the borrower's data against each lender's criteria. Depending on how the platform is configured, applications can route to multiple lenders at the same time or follow a prioritized sequence. Either way, the matching happens in seconds.
The routing logic considers factors like credit profile, industry, revenue, and loan amount. Lenders with criteria that align with the borrower's profile receive the application first.
Waterfall financing and decline recovery
Waterfall financing is the automatic process of passing declined applications to secondary lenders. If the first-priority lender declines, the application cascades to the next lender in line, and then the next if needed.
This decline recovery mechanism captures deals that would otherwise be lost. A borrower who doesn't fit one lender's credit box might be a strong candidate for another. The waterfall ensures every viable application gets a fair shot at approval.
Offer comparison and digital completion
In the Federal Reserve Banks' 2025 Small Business Credit Survey, 60% of online lender borrowers said actual borrowing costs were higher than expected—versus 37% at small banks and 32% at large banks.
Approved borrowers receive multiple offers they can compare side by side, which makes cost transparency critical. From there, they select their preferred terms, complete e-signatures, and move to funding without leaving the platform. The entire journey stays cohesive, from first click to capital in hand.
Benefits of multi-lender orchestration
The advantages show up on both sides of the lending equation. Platforms and brands gain operational efficiency, while borrowers get better outcomes and faster access to capital.
Faster speed to funding
Pre-qualified offers hosted on Lendflow drive an average of 42% faster speed to funding.
Pre-qualified offers and automated workflows compress the timeline significantly. What used to take days can happen in hours when routing, document collection, and lender communication all run automatically.
Reduced operational overhead
Lendflow's embedded finance customers operate with 80% smaller teams while converting similar funding volumes.
Manual lender management consumes resources quickly. Someone has to track applications, follow up with lenders, chase documents, and update borrowers on status. With orchestration handling routing, document collection, and status updates automatically, teams stay lean even as volume grows.
Automation handles the repetitive work, so people can focus on higher-value tasks.
Higher approval rates
Access to diverse lenders with varied credit criteria increases the likelihood that any given application finds a match. A borrower declined by one lender might be a strong fit for another with different underwriting standards. Orchestration makes that handoff seamless and automatic.
Improved borrower experience
Unified application, document upload, and status tracking create a cohesive journey. Borrowers aren't bouncing between systems or wondering where their application stands. They apply once and watch progress in one place, which reduces confusion and abandonment.
Expanded lender market reach
For lenders, joining an orchestration network opens access to high-intent, pre-qualified deal flow through embedded channels. Instead of building expensive direct-to-borrower acquisition infrastructure, lenders tap into existing platforms where SMBs already transact.
Risk diversification across capital sources
The Kansas City Fed's Q1 2026 Small Business Lending Survey found about 10% of responding banks, on net, tightened small business credit standards—continuing a four-year tightening trend.
Spreading deals across multiple lenders reduces concentration risk. If one lender tightens their credit box or exits a market, the platform's funding capacity doesn't collapse. Other lenders in the network absorb the volume, which keeps operations stable.
Multi-lender orchestration and embedded lending
Embedded lending refers to financing that appears natively inside a non-financial product. A SaaS platform might offer working capital to its users, or a marketplace might provide invoice factoring at checkout. In both cases, the financing feels like part of the core product rather than a separate experience.
Multi-lender orchestration is the infrastructure that makes embedded lending practical at scale. Without it, brands would need to build and maintain direct relationships with each lender, handle compliance workflows separately, and manage borrower communication across multiple systems.
The implementation typically involves plug-and-play tools like embedded widgets, landing pages, and APIs. Skip months-long build cycles—use pre-built components to launch embedded lending in days rather than quarters. The orchestration layer handles lender connectivity, consent management, and borrower communication behind the scenes.
Brands using this approach can monetize their customer relationships through financing while maintaining full control over the user experience. The brand stays front and center, and the orchestration platform powers everything underneath.
When your business benefits from multi-lender orchestration
Certain signals indicate orchestration would add meaningful value to your operation:
- You manage multiple lender relationships manually, and integration complexity is slowing you down
- Approval rates suffer because your current lender's credit box is too narrow for your applicant mix
- Borrowers abandon applications due to fragmented or slow experiences
- You want to offer embedded financing but lack infrastructure to manage lender networks
- Volume is growing, but adding headcount to handle it isn't sustainable
If two or more of these apply, orchestration likely solves real problems in your workflow.
Best practices for multi-lender orchestration
Implementation details matter. The difference between high-performing orchestration setups and underperforming ones often comes down to how the system is configured and maintained.
1. Design decline waterfalls that maximize approval
Structure lender priority and fallback logic intentionally. Prime lenders might sit at the top, with alternative and specialty lenders positioned to catch applications that don't fit traditional criteria. The goal is capturing deals that would otherwise be lost after a single decline.
Consider factors like lender response time, approval rates by segment, and funding speed when setting the order. A well-designed waterfall can significantly increase overall approval rates without any changes to the applicant pool.
2. Centralize consent and compliance workflows
Unified consent flows and regulatory alignment across lenders prevent patchwork compliance headaches. When every lender operates under consistent consent management, audits become simpler and borrower trust increases.
Fragmented compliance creates risk. Centralizing consent collection, data sharing agreements, and disclosure requirements reduces that risk while streamlining the borrower experience.
3. Prioritize borrower experience across lender handoffs
Even when multiple lenders evaluate an application behind the scenes, the borrower's experience stays seamless and branded. Inconsistent UX during handoffs erodes trust and increases abandonment.
The borrower doesn't need to know which lender is reviewing their application at any given moment. What matters is that the experience feels cohesive from start to finish.
4. Use real-time data to inform routing decisions
Live credit signals and current business data improve lender matching accuracy. Stale information leads to misrouted applications and wasted time for everyone involved.
Real-time data also enables dynamic routing adjustments. If a lender's criteria change or their capacity shifts, the orchestration layer can adapt without manual intervention.
5. Automate document collection and verification
Document automation covers upload, extraction, and validation. Manual document handling creates bottlenecks that orchestration is designed to eliminate.
Tools like AI-powered document analyzers can extract structured data from bank statements, tax returns, and IDs automatically. This speeds up underwriting and reduces errors from manual data entry.
Challenges to plan for before you launch
Orchestration removes lender-by-lender build work, but three challenges still need a plan before go-live:
- Legacy system integration: Older origination, CRM, and servicing systems may need API work before they can pass borrower data to the orchestration layer
- Inconsistent lender data formats: Each lender may expect different fields, files, and decision responses, so data must map to one normalized borrower profile
- Compliance logging and consent records: Every consent event, data share, and lender decision needs a retrievable record for audits and disclosures
Skip custom builds for each lender—use pre-built widgets, landing pages, and APIs to keep integration work contained.
How to evaluate multi-lender orchestration platforms
Decision-makers comparing platforms benefit from a structured evaluation framework. Here are the key criteria to consider:
Questions to ask every vendor:
- Can lenders evaluate one normalized borrower profile?
- Can you change routing or waterfall rules without a code release?
- Can you reconstruct a past decision, including inputs?
- Does the borrower stay in one branded experience across lender handoffs?
Lendflow Connect, for example, offers a network of 75+ specialty and bank lenders, SOC 2 Type II compliance, and deployment timelines as fast as two weeks for widgets or 30-45 days for full API integrations.
Why multi-lender orchestration drives the future of SMB lending
In the 12 months ending March 2025, $1.5B+ in offers were made on Lendflow's platform—a measure of the scale orchestration enables.
The direction is clear: SMB financing is becoming embedded, automated, and multi-lender by design. Brands want to offer financing where their customers already transact. Lenders want efficient access to qualified deal flow. Borrowers want fast, simple funding experiences.
Multi-lender orchestration sits at the center of this shift, connecting all three parties through infrastructure that didn't exist a few years ago.
The platforms that adopt orchestration early gain compounding advantages: better approval rates, faster funding, and leaner operations. Those relying on single-lender relationships or manual processes face increasing pressure as borrower expectations rise and competition intensifies.
Ready to see how orchestration works in practice? Book a demo or talk to our team to explore how Connect, Intelligence, and Automate can power your lending infrastructure.
FAQs about multi-lender orchestration
Does applying through a multi-lender platform affect credit scores?
Most multi-lender platforms use soft credit pulls during initial matching, which do not impact credit scores. Hard pulls typically occur only after the borrower selects a specific offer and moves toward funding.
How long does it take to implement a multi-lender orchestration platform?
Implementation timelines vary by integration method. Embedded widgets can launch in under two weeks, while full API integrations typically take 30-45 days depending on customization requirements.
What financing types are supported by multi-lender orchestration?
Multi-lender orchestration platforms commonly support term loans, lines of credit, MCAs, invoice factoring, equipment financing, SBA loans, and purchase of receivables. Coverage depends on the specific lender network.
How do lenders benefit from joining a multi-lender network?
Lenders gain access to pre-qualified, high-intent deal flow through embedded channels. This expands market reach without building direct-to-borrower acquisition infrastructure.
What is the difference between multi-lender orchestration and loan aggregation?
Loan aggregation typically compares offers from a static list of lenders. Multi-lender orchestration goes further by dynamically routing applications, managing decline waterfalls, and automating the full lifecycle from application through funding.
Is multi-lender orchestration the same as a financing waterfall?
No—a financing waterfall is one routing method inside multi-lender orchestration, passing a declined application to the next lender in a set sequence. Orchestration covers the full lifecycle: data collection, consent, routing logic, offer comparison, and funding. A waterfall handles declines; orchestration coordinates every step from application to capital in hand.
What is data orchestration in lending?
Data orchestration in lending coordinates credit, bank, identity, and document data sources into one workflow. Instead of pulling each source separately, the orchestration layer collects, structures, and passes data to decisioning and routing. Lenders evaluate a consistent borrower profile, and decline waterfalls can move applications to the next lender without re-collecting information.
How is multi-lender orchestration similar to payment orchestration?
Both route each transaction or application through one layer to the best-fit provider, such as a payment processor or a lender. Multi-lender orchestration differs because routing weighs each lender's credit criteria—credit profile, industry, revenue, and loan amount. The result is an approval decision and offers rather than a processed payment.